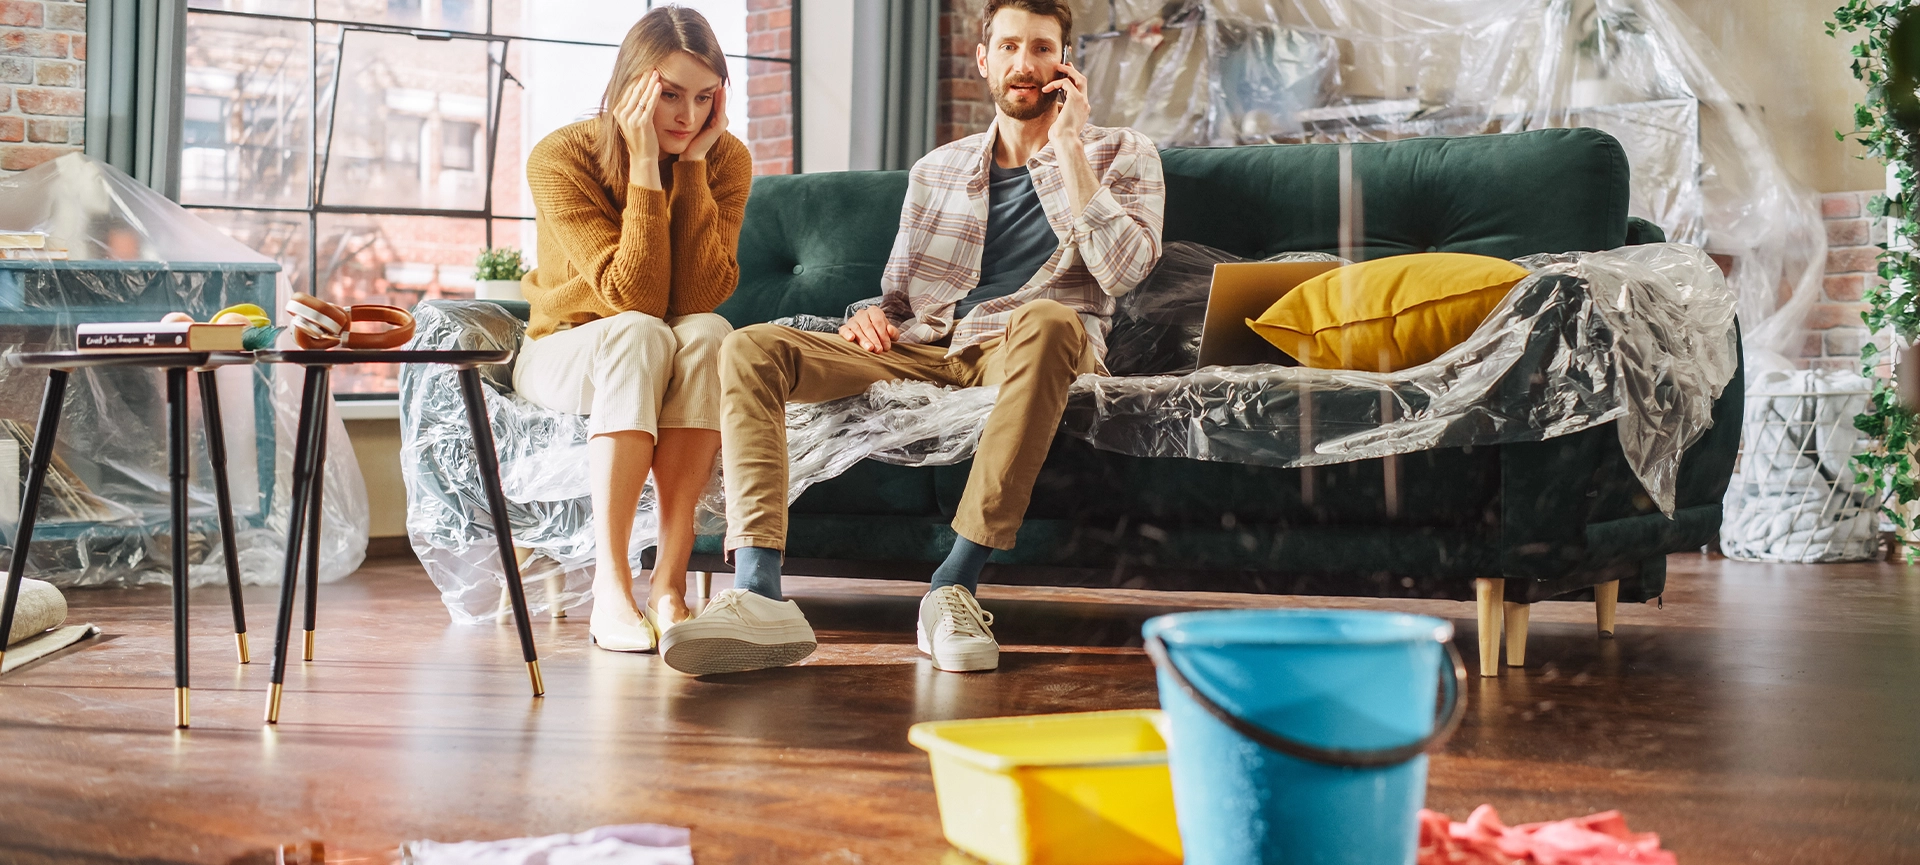

Water damage is one of the most common and costly claims for renters. Whether it’s a burst pipe, a leaky roof, or an overflowing bathtub from the upstairs unit, the financial impact can be significant.
If you rent, you might assume your landlord’s insurance will cover the damage, but that’s not always the case. Tenant insurance can help protect you, but coverage depends on the source of the water, your policy details, and any exclusions in place.
Understanding Tenant Insurance and Its Role
Tenant insurance, sometimes called renter’s insurance, is designed to protect your personal belongings and liability when you don’t own the property. While the landlord’s insurance covers the building structure, it usually doesn’t extend to your personal property or additional living expenses if you have to move out temporarily.
Water damage coverage under tenant insurance can apply in several situations, but it’s not all-inclusive. Knowing what’s covered and what’s excluded can save you from expensive surprises during a claim.
Related Article: What Does Renters Insurance Cover?
Types of Water Damage Commonly Covered
Tenant insurance policies typically cover sudden and accidental water damage. This means the event must have been unforeseen and not caused by neglect. Common covered situations include:
- Burst pipes: If a pipe inside your unit suddenly bursts and damages your furniture, electronics, and clothing.
- Appliance malfunctions: A washing machine or dishwasher hose failure that causes water to leak onto your belongings.
- Accidental overflow: Water damage caused by a sink or bathtub overflow you couldn’t have reasonably prevented.
- Fire suppression: Water damage caused by sprinkler systems or firefighting efforts.
These events are usually covered because they are sudden, unexpected, and directly damage your insured belongings.
What’s Often Excluded from Coverage
Not all water-related issues are covered under tenant insurance. Insurers commonly exclude:
- Flood damage: Rising water from heavy rain, melting snow, or overflowing rivers typically requires separate flood insurance.
- Sewer backup: Unless you’ve purchased an add-on, damage caused by backed-up sewers or drains is excluded.
- Gradual leaks: Damage from long-term, undetected leaks, such as a slow drip under the sink, is usually not covered.
- Poor maintenance: If the damage was due to your negligence or failure to maintain appliances, it might be denied.
These exclusions make it important to understand your policy and consider optional endorsements for broader protection.
Additional Living Expenses Coverage
If water damage makes your rental uninhabitable, many tenant insurance policies include Additional Living Expenses (ALE) coverage. This can pay for temporary accommodation, meals, and other increased costs of living while repairs are completed. ALE coverage can be critical when you’re suddenly displaced, allowing you to maintain stability while your home is restored.
Liability Protection for Water Damage to Others
Tenant insurance also provides personal liability coverage, which can protect you if your actions cause water damage to another unit or the building. For example, if you accidentally leave the bathtub running and water seeps into the unit below, liability coverage can pay for repairs and any legal expenses if you’re sued.
This aspect of tenant insurance is particularly important in multi-unit buildings where one incident can affect multiple neighbours.
How to Check Your Policy for Water Damage Coverage
Insurance policies can be complex, but knowing where to look will help you understand your water damage protection:
- Review the “Perils Insured Against” section – This outlines which events are covered and under what conditions.
- Look for endorsements and exclusions – These can expand or limit your coverage. Common water damage add-ons include sewer backup or overland flood protection.
- Check coverage limits – Some water damage claims may have specific limits separate from your overall personal property coverage.
- Ask your broker for clarification – If you’re unsure, a broker like Buckler Insurance can review your policy and recommend adjustments.
Related Article: How to File a Claim on Your Tenants’ Insurance in Ontario?
Common Exclusions and Pitfalls
Even with coverage in place, there are common pitfalls that can lead to denied claims:
- Failing to act quickly: Insurance companies expect you to take reasonable steps to prevent further damage after a leak.
- Lack of documentation: Without photos, receipts, and a clear record of the incident, your claim might be delayed or denied.
- Improper installation: Damage caused by poorly installed appliances or plumbing may be excluded.
- Unreported changes: Not informing your insurer about renovations or appliance upgrades could affect your claim.
Understanding these pitfalls ensures you know how to respond if water damage occurs.
Tips to Enhance Water Damage Protection
To reduce your risk and strengthen your insurance protection:
- Install water leak detectors: These can alert you to leaks before they cause major damage.
- Keep appliances maintained: Regularly check hoses, connections, and seals.
- Add sewer backup and overland flood coverage: If you live in an area prone to these risks, optional coverage can be invaluable.
- Know your shut-off valves: Being able to quickly stop water flow can limit damage.
- Work with an insurance broker: A broker can ensure your policy matches your needs and budget.
The Role of Your Landlord’s Insurance
Your landlord’s insurance generally covers the building structure, fixtures, and common areas. However, it doesn’t protect your personal property or provide ALE if you’re displaced. In a water damage event, their insurance might repair the building, but you’d be responsible for replacing your belongings unless you have tenant insurance.
This distinction is one of the main reasons renters’ insurance is so valuable.
Why Working with a Broker Matters
Policies vary widely between insurers. A broker like Buckler Insurance, serving Ontario residents since 1959, can help you compare coverage options from multiple providers, explain terms in plain language, and ensure you’re not missing critical endorsements like flood or sewer backup protection. We can also guide you through claims to make the process smoother and less stressful.
Related Article: How to Choose the Right Tenants’ Insurance Policy in Ontario?
Real-Life Example: The Cost of Being Uninsured
Consider a tenant whose upstairs neighbour’s dishwasher hose burst overnight, sending water into their apartment. Without tenant insurance, they would pay out of pocket for:
- Replacing damaged furniture and electronics
- Temporary hotel stays during repairs
- Clothing and personal item replacement
With tenant insurance, these costs could be covered, significantly reducing the financial and emotional burden.
Preparing for the Unexpected
Water damage is unpredictable, but you can take steps to limit its impact:
- Keep an inventory of your belongings with photos and receipts.
- Update your coverage annually to match your current lifestyle.
- Know the claims process for your insurer.
- Address small leaks promptly to prevent major losses.
Taking proactive measures helps you recover faster and avoid disputes with your insurer.
Related Article: Tenants Insurance FAQs
Recommended Next Steps
If you rent, review your current policy or get a quote for tenant insurance that includes the water damage coverage you need. Speak to a broker to identify optional endorsements that make sense for your location and property type.
Make sure you understand both your rights and responsibilities so you can act quickly if water damage strikes.
Stay Dry and Secure with the Right Tenant Insurance
Water damage can happen quickly and cause lasting problems. The right tenant insurance policy ensures you’re financially protected, whether it’s a burst pipe in your unit or an unexpected flood in the building. Work with Buckler Insurance to find comprehensive coverage that addresses your unique needs.
Call us today to review your tenant insurance options and get peace of mind before the next leak or storm hits.